Receipt or Invoice: Two Records, Different Jobs
Receipt or invoice? Learn which document records a charge, which confirms payment, and how to match them so you can spot an unclear or open balance.
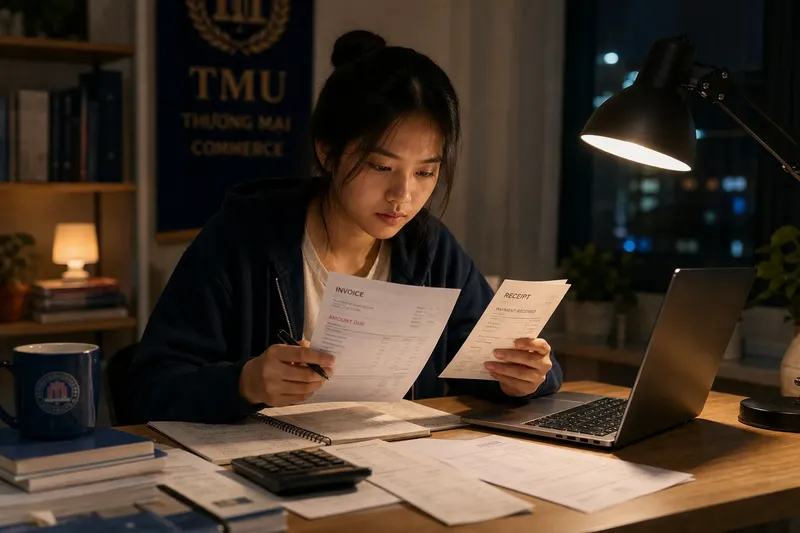
A receipt or invoice answers a different question about a sale: one records a charge, the other records payment. If you are sorting a purchase from a shop or a commerce exercise at Trường Đại học Thương mại (TMU), check what the document says happened before relying on its title.
What does an invoice record?
An invoice identifies a seller and buyer, describes goods or services, states a charge, and may set payment terms or a due date. It requests payment. If the buyer has not paid, the invoice remains a record of what is owed, even if it was issued after delivery.
A receipt ordinarily acknowledges that a seller received payment. It may show the transaction, amount received, date, and payment method. A receipt can document a partial payment; it does not automatically establish that the full balance is settled or that goods were delivered in good condition.
Other documents record other stages. A purchase order records what a buyer requested, a delivery note records what was handed over, and a credit note records an adjustment. Calling all of them “the bill” saves a word and loses a distinction.
Why can the document title mislead?
People use “bill,” “invoice,” and “receipt” loosely. A restaurant may call its pre-payment document a bill, while an online order page may combine item details with a payment confirmation. In either case, the contents matter more than the heading.
Timing does not settle the question. An invoice can arrive after goods do and still request payment. A receipt can appear at checkout without a separate invoice. Look for whether the record states an amount due or confirms an amount received.
A document marked “paid” also needs context. It may show that one payment was applied without proving that the entire account is settled. Conversely, an invoice may later show a zero balance while remaining the document that itemized the original charge.
How do you check a receipt or invoice?
Read for the transaction stage, then match the details to the purchase. Use these checks to decide whether the record answers the question you need resolved:
- Heading and wording: If the body requests payment or lists an amount due, treat it as a charge record; if it confirms money received, treat it as payment evidence. If neither is clear, ask the issuer to identify the document’s purpose.
- Seller and buyer: If the named parties match the transaction, keep checking; if a party is wrong, ask the issuer for a correction and retain the original with it.
- Goods or service: If the description identifies the purchase, file it with that transaction; if it is vague or unrelated, request an itemized or corrected record.
- Amount and date: If the amount and date fit the agreed charge or payment, record which one they describe; if they do not, compare against the order and payment records, then ask about any unexplained difference.
- Payment and balance: If the document shows the amount received and any remaining balance, use that status to track the account; if it shows only “paid” without clarifying the amount or scope, ask whether the full invoice was settled.
- Related records: If an invoice, payment confirmation, and receipt share a transaction reference, store them together; if they do not, add a separate note linking them only after the seller confirms the match.
Say you have an invoice for notebooks marked “amount due,” a bank notice showing a transfer, and no receipt. The invoice identifies the charge; the bank notice shows money left the account but may not show how the seller applied it. You ask the seller to confirm whether that transfer belongs to the invoice and request a receipt or written acknowledgment. If the seller confirms the match, keep that acknowledgment with both records; if not, preserve the bank notice and ask what transaction the payment was applied to.
What problems arise from using the wrong record?
An invoice is filed as proof of payment. If it lists only an amount due, it does not establish that the buyer paid. Keep it as the charge record and request a receipt or payment acknowledgment; if it clearly records payment received, retain it as evidence of both the charge and that payment.
A receipt is expected to explain the whole purchase. If it confirms payment but lacks item details, keep the order confirmation or invoice alongside it. If those records disagree about what was supplied, ask the seller to clarify rather than treating the receipt as a delivery record.
The payment and invoice amounts differ. A deposit, split payment, discount, refund, or added charge may explain the gap. If the other records account for the difference, note the reason and keep them together; if they do not, ask the seller for an explanation and preserve the original documents rather than editing them.
A record is missing or duplicated. Check email, the seller’s account page, the point-of-sale app, and the bank or card statement for a transaction reference. If you contact the seller, name the record you need—an itemized invoice, receipt, or payment-application confirmation. “Please send the paperwork” is brief, but does not tell anyone what to send.
The record names the wrong party or transaction. If the details point to an outdated account or a different order, contact the issuer with the reference and request a correction or written explanation. Keep the original with the correction so the change has context.
How should a business connect the records?
A seller can link an invoice and receipt through a shared transaction reference. The invoice records the charge and terms; the receipt records payment and, where relevant, the remaining balance. For a partial payment, record the amount received separately from the amount still due. When the account is settled, update its status without erasing the payment history.
A buyer can keep the invoice, payment confirmation, receipt, and relevant delivery record together. A bank statement may corroborate a transfer without identifying the goods, so it does not always replace a seller’s acknowledgment. Clear filenames with the seller and transaction reference make these records easier to retrieve than a folder of files named “final.”
Scan paper receipts when useful, but keep originals if needed for a return, warranty claim, or formal accounting process. Store financial records where access is limited to people who need them. For tax or regulatory requirements, follow applicable rules and consult a qualified accountant or adviser when necessary.
Which receipt or invoice questions come up?
Can an invoice count as a receipt?
It can serve both purposes if it clearly records payment received and identifies the amount paid. An invoice that only lists a charge does not establish payment.
Can a receipt replace an invoice?
A detailed receipt may be enough for an ordinary purchase record. If you need itemized charges, payment terms, or a document addressed to a business, request an invoice as well.
What if the seller has not sent a receipt?
Keep the available card slip, bank record, or online payment notice, then ask the seller for an acknowledgment tied to the transaction. A bank record may show a transfer without showing how the seller applied it.
Does “paid” mean the account is settled?
Not necessarily; the mark may refer to one payment rather than the whole invoice. Check the amount and remaining balance, or ask the issuer for written clarification.
When is extra paperwork unnecessary?
For a minor purchase with a clear itemized receipt and a matching payment confirmation, asking for a separate invoice may add little. A useful receipt or invoice set answers the specific question at hand: what was charged, what was paid, and whether anything remains due.
Ask for an invoice when you need the charge and its terms; ask for a receipt when you need acknowledgment of payment. If a deposit, adjustment, or disputed balance complicates the account, keep the related records together and seek clarification before treating it as settled. For formal accounting or regulatory decisions, consult a qualified professional.